Market overview and structural scope of the Nanotechnology Services Market
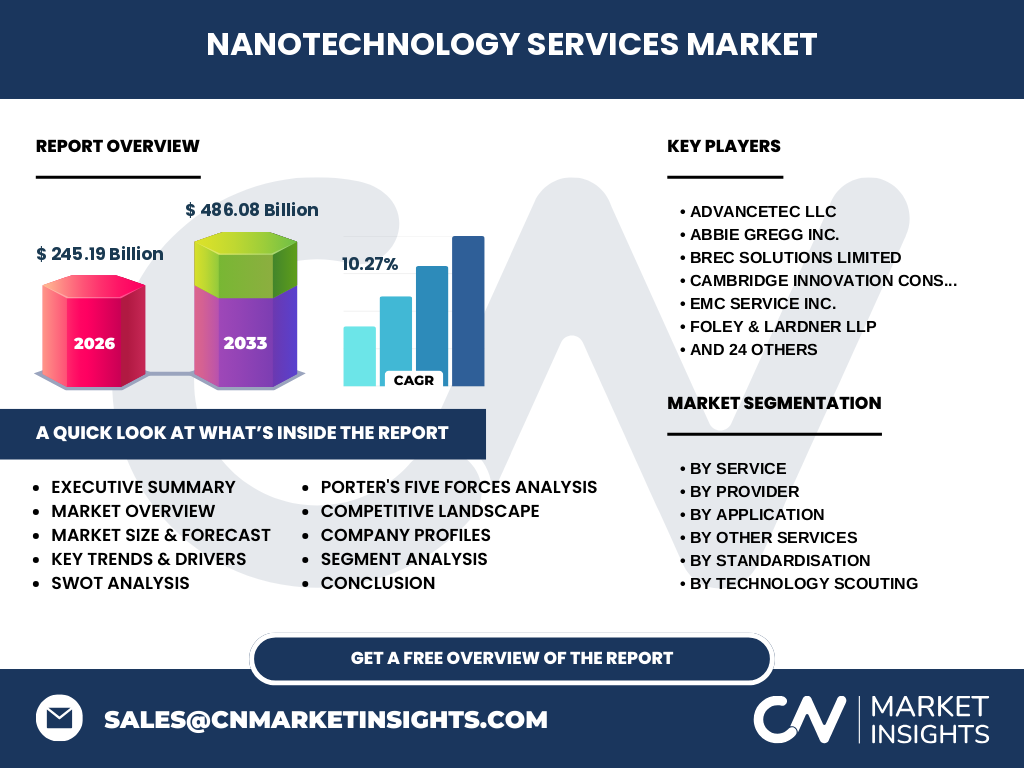
Our proprietary analysis indicates the Nanotechnology Services Market size reaches 245.19 Billion. This sector encompasses high-value consulting, R&D outsourcing, and regulatory compliance essential for scaling carbon nanotubes, quantum dots, and advanced nanomaterials across global manufacturing ecosystems.
Structural Growth Drivers, Restraints, and Opportunities in Nanotechnology Services
The market thrives on escalating demand for precision therapeutics and nanoelectronics. However, stringent compliance frameworks by agencies like the EPA and FDA act as key restraints. Strategic opportunities emerge in providing specialized commercialization services and nanomaterial safety standardization.
Emerging Trends and Technological Shifts Shaping Nanotechnology Services
The shift toward commercializing nano-optics and photonics is accelerating. Market trends reveal that firms leveraging advanced characterization tools and intellectual property management gain competitive advantages, particularly in integrating nanomaterials into existing IT hardware supply chains.
COVID-19 Impact Analysis and Post-Pandemic Recovery Trajectory
Pandemic-induced supply chain bottlenecks temporarily delayed R&D projects involving advanced nanomaterials. Post-COVID recovery has been robust, driven by surging investments in nanomedicine and robust biosecurity innovations supported by firms like Abbie Gregg Inc. and AdvanceTEC LLC.
Competitive Benchmarking and Market Concentration Dynamics
The Nanotechnology Services Market industry trends highlight a moderately consolidated landscape featuring specialized innovators alongside major engineering giants. Companies such as M+W Group GmbH and HDR Inc. dominate cleanroom design, while boutique firms like BREC Solutions provide critical regulatory navigation.
Executive Summary of the Nanotechnology Services Market
Valued at 245.19 Billion, the market is poised for significant expansion. Our research underscores that R&D outsourcing and regulatory briefing services represent the fastest-growing revenue streams, driven by rigorous safety validation requirements for commercialized nanomaterials.
Long-Term Market Forecast and Expansion Projections from 2027 to 2033
Our forecasting models project the Nanotechnology Services Market analysis to expand to 486.08 Billion by 2033. This trajectory represents a robust compound annual growth rate (CAGR) of 10.27%, fueled by widespread industrial adoption of nanotechnology.
Comprehensive Segmentation Breakdown Across Service and Application Pillars
Segmentation spans multiple critical vectors: By Service (Research and Development, Information Tracking, Technology Scouting, Standardization, Regulation Briefings), By Provider (Large Enterprise, Small and Medium Enterprise), and By Application (Pharmaceuticals, Medical Equipment, Food and Beverages, IT).
Regional Market Distribution and Geographic Performance Analysis
Geographic performance indicates strong dominance in North America and Europe, supported by dense clusters of biotechnology hubs and advanced semiconductor fabrication facilities. Asia-Pacific demonstrates the highest regional growth velocity due to aggressive government funding in nanoelectronics.
In-Depth Regional Review and Localized Market Constraints
Regional analysis reveals that North American growth is anchored by rigorous FDA and EPA oversight, demanding specialized regulatory compliance. Meanwhile, European markets focus heavily on standardization and environmental impact assessment guidelines managed by advisory entities like Innovationsgesellschaft mbH.
Strategic Positioning and Company Profiles of Industry Leaders
Industry leaders deploy distinct strategic positioning: DuPont de Nemours Inc. and Arkema S.A. drive material innovations, while specialized consultants like Cambridge Innovation Consulting and Malsch TechnoValuation deliver targeted technology scouting and risk assessment services.
Porter's Five Forces Analysis of the Competitive Ecosystem
Industry rivalry is intense, shaped by moderate buyer power due to high switching costs in technical R&D services. Supplier power remains low for commoditized inputs but high for proprietary characterization tools, while the threat of substitution is mitigated by bespoke nanodevice solutions.
SWOT Analysis of the Nanotechnology Services Sector
Key strengths include deep scientific expertise and proprietary databases. Weaknesses involve high initial capital outlays. Opportunities lie in emerging nanomedicine applications, whereas threats stem from evolving, unpredictable international regulatory frameworks governing nanomaterial toxicity.
Value Chain Analysis from Raw Materials to End-User Commercialization
The value chain flows from raw precursor synthesis through specialized R&D and pilot-scale prototyping. Upstream providers supply engineered nanoparticles, while midstream service providers handle regulatory briefings, intellectual property filing, and scalable commercialization for end-use pharmaceutical and IT markets.
Investment Insights and High-Potential Growth Areas for Stakeholders
Investors should prioritize service providers specializing in nanoelectronics R&D and international standard compliance. These high-potential domains offer resilient margins and insulate stakeholders against shifting cross-border trade regulations on advanced nanomaterials.
Conclusion and Strategic Takeaways for Industry Stakeholders
Capturing future upside in this 486.08 Billion market requires strategic partnerships between material producers and compliance specialists. Firms that successfully bridge laboratory innovation with standardized commercialization will capture disproportionate market share.
Rigorous Research Methodology and Data Triangulation Protocols
Our baseline estimates are established through rigorous triangulation, combining primary stakeholder interviews with C-level executives, exhaustive analysis of trade registries, and secondary macroeconomic indicators sourced from international patent offices and standardization bodies.
Scope of the Report and Analytical Parameters
This report evaluates global service providers across R&D, compliance, and commercialization vectors. Limitations exclude localized underground laboratories and unregistered nanoscale manufacturing facilities operating outside formal international standardization networks.
Recent Developments, Strategic Partnerships, and Corporate Innovations
Recent market dynamism is highlighted by strategic alliances between specialized imaging firms like Nanonics Imaging Ltd. and photonics innovators such as Voyant Photonics, alongside proactive regulatory alignment initiatives spearheaded by legal leaders like Foley & Lardner LLP.